


Depot charging and the grid: the two-year queue that decides your electrification date
Depot charging and the grid: the two-year queue that decides your electrification date
Trucks can be delivered in months; multi-megawatt grid connections take years in congested zones. How to sequence grid applications, size a depot charging build, and why energy strategy comes before vehicle selection.
2026-08-08 · WattTonne review desk
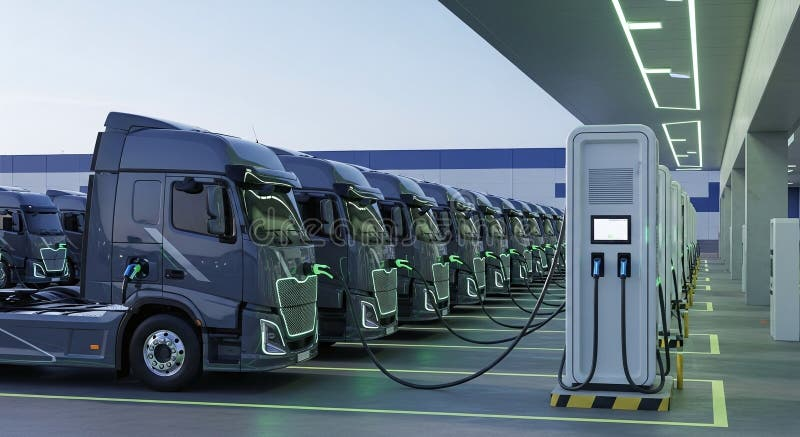
Ask any fleet that has actually electrified what the critical path was, and none answer “the truck”. The critical path is the grid connection — and in the congested zones of the Netherlands, Flanders and urban Germany, multi-megawatt connections are quoted in years, not months. The fleet that orders trucks before filing its grid application has the sequence exactly backwards.
The sequence that works. (1) Energy audit: map duty cycles, dwell times and daily energy per vehicle — a 40-truck regional depot doing 250 km/day at 1.1 kWh/km needs roughly 11 MWh delivered nightly. (2) Grid application at target capacity, filed immediately — capacity reservations in congested areas are the scarce asset; even a staged build wants the full headroom requested now. (3) Charger architecture sized to dwell time, not to maximum power: overnight fleets rarely need megawatt charging at the depot; 40–150 kW per position with smart load management covers most duty cycles at a fraction of the connection cost. (4) Tariff and flexibility: depot electricity economics live or die on tariff structure — static peak pricing punishes simultaneous charging, while dynamic tariffs plus load management routinely cut effective energy cost 20–40%. (5) Only then: vehicle order matched to the infrastructure delivery date.
The numbers to argue with. Depot energy at €0.15–0.25/kWh (before optimisation) against public fast charging at €0.60–0.90 — at 1.1 kWh/km and 100,000 km/year, the tariff choice alone is worth €40,000–70,000 per truck over five years. Danish fleet data quantifies the same gap in kroner (0.75–1.07 vs ≈3.00 DKK/kWh). Infrastructure capex per truck typically lands at €15,000–60,000 allocated, before grants — the UK’s Depot Charging Scheme (70% to £1 million) and various Enova/RVO instruments subsidise exactly this line.
The traps. Sizing the connection to diesel-era assumptions (not every truck charges every night); ignoring the DSO’s congestion map when choosing a new depot site; signing vehicle delivery dates before the energisation date is in writing; and forgetting that charger uptime, not charger count, is the operational KPI — a 40-stall depot at 85% uptime strands six trucks nightly.
WattTonne’s read. Treat your grid application as the first truck you buy. Fleets that internalise this sequence electrify on schedule; those that don’t explain to their boards why €300,000 trucks are parked waiting for a transformer.
- WattTonne fleet infrastructure research
- Danish depot-vs-public energy data (MDPI 2026)
- UK Depot Charging Scheme documentation
- DSO congestion disclosures (Fluvius, Dutch netbeheerders)
Evidence dated as shown. Corrections and manufacturer evidence: hello@wattonne.com. WattTonne assessments are never for sale; affiliations disclosed on the About page.